What is Phygital?
Phygital is not a marketing term. It is a fundamental architectural principle: the deliberate engineering of seamless continuity between physical interactions and digital services within a single, governed transaction context.
A customer can begin a mortgage application on their oneWallet, continue it at a smart kiosk in a community hub, receive biometric verification at a POI Appliance, and complete identity-verified document signing at a physical branch – all within the same governed session, with a single consent record and an unbroken audit trail.
This is fundamentally different from "mobile-first" or "digital transformation." Those approaches retrofit digital onto existing physical infrastructure. Phygital engineers both together from first principles – governed at every touchpoint by the same Constitutional OS.
Digital Channels
Mobile apps, web portals, API integrations – any digital touchpoint governed by the same Constitutional OS
Physical Touchpoints
ATMs, smart kiosks, community HUBs, LockerShops, branch POIs – every physical form factor unified on the same platform
Unifying Branch Appliances, Smart Kiosks & Digital Customer Journeys
Conventional banking and commercial enterprises operate through fragmented channel silos – treating physical branch networks, ATM fleets, smart self-service kiosks, and mobile applications as disconnected software stacks. The onePOI Phygital Omnichannel platform breaks this legacy divide by establishing an XFS4IoT-compliant appliance mesh governed by a single Constitutional OS. As demonstrated in this executive briefing, a citizen or merchant can initiate a transaction on their mobile wallet, verify biometrics at a community counter, and conclude cash dispensation or credential issuance at an unattended terminal – with uninterrupted session state, instant account-to-account (A2A) settlement, and zero cross-channel data leakage.
Engineered for Institutional Margins.
Adopted for Human Sovereignty.
Every capability across the Salient Innovation Set delivers an immediate, symmetrical return: radical margin recovery for the enterprise tenant, paired with frictionless dignity and absolute cryptographic safety for the citizen.
How the Tenant Expands Margins
Transforming operating models from defensive cost centres into agile, shared revenue engines through multi-tenant pooling and mathematical compliance.
-
CapEx Pooling & No Single-Tenant Hardware
POI Appliances run white-label on co-funded premises. Reach 50 commercial catchments without funding 50 proprietary branch builds.
-
Zero Interchange & Flat-Fee Clearing
Instant Account-to-Account rails (SEPA Instant / PayShap) bypass 1.5–3.5% card scheme tolls with predictable, flat sub-cent clearing fees.
-
Compliance by Construction
Agreement DAGs enforce statutory mandates at wire speed; non-compliant states cannot execute, eliminating retrospective audit penalties.
-
Accelerated Partner Onboarding
Pre-verified BIAN and ArchiMate capability components compress multi-firm integration cycles from quarters to days.
Why the Customer Loves Using It
Delivering sovereign dignity and verifiable security where users never surrender control over their identity, consent, or funds.
-
Nothing Stored to Steal
Credentials remain in the user's oneWallet. A breach of a merchant's server reveals zero identity records, protecting citizens completely.
-
One Pattern, Everywhere
The same intuitive tap-and-confirm interaction works seamlessly at a high-street kiosk, transit hub, EV charger, or smartphone.
-
Delegated Authority, Never Escalated
Autonomous AI agents carry single-use, bounded warrants; an agent checking information cannot escalate its authority to transfer money.
-
Payments That Do Not Fail
When a payment network degrades, the transaction reroutes with authentication preserved – zero declines, zero repeated entries.
Universal. Unified. Ubiquitous.
U³ Phygital Channel Matrix
What: A 4×3 grid: rows are the U³ properties (Universal · Unified · Ubiquitous); columns are channel types (Mobile/Wallet · POI Appliance · Web/Browser · Voice/Assistant). Each cell shows the same governed service running through that channel with the same Agreement DAG, same LAHE, same identity. A single transaction (e.g. payment + KYC + consent) shown threading horizontally across all channels.
Why: U³ is the most-claimed and least-illustrated concept on the site. Showing the same service spanning every channel – under one governance fabric – makes the abstraction concrete and immediately refutes the 'just another omni-channel' read.
Three non-negotiable properties engineered into every layer of the omnichannel architecture.
Universal
Every service available to every customer, regardless of their device, literacy level, physical ability, or geographic location. The platform is designed to leave no one behind – serving the fully digital native and the cash-preferring elder with equal capability.
- Accessible to the digitally excluded
- Multi-language and multi-currency
- Rural and urban deployment models
- Offline-capable edge processing
Unified
A single, coherent experience regardless of which channel a customer uses. No siloed journeys, no "please call this number to continue," no starting over. The session, the identity, the consent, and the context travel with the customer across every touchpoint.
- Single customer identity across channels
- Session continuity: start mobile, finish physical
- Shared consent and preference record
- Single unbroken audit trail
Ubiquitous
Available everywhere a customer needs it – embedded into retail environments, public spaces, healthcare settings, agricultural co-ops, and transport hubs. The platform deploys its capability to where the customer already is, not where the bank wants them to be.
- Multi-sector physical form factors
- Co-location in existing community infrastructure
- Shared CapEx – viably deployed in low-density areas
- Edge-compute resilience in low-connectivity zones
POI Appliance Form Factors
Every physical touchpoint is a multi-tenant POI Appliance – shared infrastructure that securely hosts multiple competing service providers simultaneously, each with complete isolation and individual brand control.
Advanced ATM / ITM
Next-generation cash and interactive teller machines hosting multiple banks simultaneously. Full biometric authentication, video teller capability, and agentic service delivery – 24/7 without staff.
Smart Kiosk / HUB
Interactive multi-service kiosks for community deployments – enabling banking, government services, healthcare triage, retail collection, and public information in a single shared appliance footprint.
LockerShop
Intelligent, temperature-controlled smart locker arrays for click-and-collect, pharmacy dispensing, meal delivery, and 3PL logistics. Multi-tenant with individual locker compartment governance.
Healthcare POI
Clinical-grade interaction appliances for patient check-in, prescription dispensing, teleconsultation, and health record access – with biometric authentication and full audit trails meeting clinical governance standards.
Agri Co-op POI
Ruggedised agricultural POI appliances for rural co-operative hubs – enabling market access, input financing, produce grading, and payment settlement for smallholder farmers with offline resilience.
Phygital Community HUB
Full-featured community service centres hosting banking, government, health, retail, and social services in a single shared space – the anchor infrastructure for the Digital Public Infrastructure (DPI) agenda.
Seven Ranked Foundational Innovations
How the foundational authority hierarchy bridges physical counters, mobile wallets, and edge AI into an insurable, universal phygital continuum.
Authority Lives in the Agreement
Authority lives in the agreement, not in the identity. When an elder uses biometric verification at an ATM or a student unlocks a locker, identity proves authenticity while the bilateral Agreement DAG carries authority to execute.
Unlawful Execution is Unavailable
Unlawful execution is a state the platform cannot enter. The commercial word is insurable. Pre-execution adjudication at physical POI endpoints creates the bounded operational loss envelope underwriters require.
Constitutional Delegation & Agent Liability
AI assistants guiding citizens at kiosks operate under signed On-Behalf-Of (OBO) delegation tokens with single-action expiry and pre-ruling GateKeeper verification, eliminating agent liability gaps.
Lawful Execution at the Counter
Pre-execution adjudication runs locally on the POI appliance hardware at the physical counter. Community hubs continue dispensing pensions, validating prescriptions, and processing payments during power cuts and network partitions.
Many Tenants, One Appliance
Multiple competing banks, parcel couriers, pharmacy dispensers, and municipal services operate simultaneously inside hardware-isolated TEE enclaves on the same physical POI footprint.
Flat Clearing & Sovereign Wallet
Direct A2A / SEPA Instant clearing over direct bank transfer rails at a predictable flat target clearing fee (near-term target state architecture, Q4 2026 / 2027 roadmap). oneWallet projects verifiable micro-claims across all phygital channels.
 Strategic Lever 01
Replay as a Product, Not a Log
Re-run any phygital interaction decision exactly as it occurred against the historical bitemporal rule stanzas.
 Strategic Lever 02
Switcher+ & Entitlement Continuity
Citizen service entitlements and health authorisations travel with the user under citizen-held agreements across all physical channels.
 Strategic Lever 03
Institutional Standards Crosswalk
Standardised on CEN XFS4IoT, BIAN Service Domains, and ISO 20022 message envelopes for universal institutional compatibility.
Phygital in Action
End-to-end Phygital Journey – one citizen, four touchpoints
What: A horizontal swim-lane: citizen starts on oneWallet (consent + identity), continues at a high-street kiosk (biometric proof), pays at a retail POS (SEPA Instant), receives a service confirmation at a Community HUB. Above the lane: the same Agreement DAG persisting across all four; below the lane: one continuous LAHE chain, time-stamped.
Why: Reviewers struggle to picture 'one session, four physical surfaces, one governed transaction'. A swim-lane converts the words into a believable, audit-able journey.
Select a sector to see how phygital omnichannel transforms the customer experience.
Maria – Small Business Owner, needs a working capital loan
Traditionally: 3 branch visits, 2 weeks, paper forms, 40% rejection rate due to thin credit files.
Maria opens oneWallet, initiates a loan application. Her agentic identity shares consented transaction history and cash flow data directly with the lender's AI.
She walks to the nearest community HUB. The kiosk recognises her session, performs biometric verification and document scanning – no forms to fill out again.
James – Grocery shopper, picks up an online order
Traditionally: separate app per retailer, separate collection process, no cross-retailer loyalty, cash excluded from digital offers.
James orders groceries via the retailer's app. His oneWallet pays instantly via agentic payment mandate – no card entry, no password.
He stops at the nearest LockerShop. A QR code from his wallet opens his compartment instantly – also collects a pharmacy prescription and a parcel, all in one stop.
Cross-retailer loyalty points accumulate automatically in his wallet – pooled across every tenant using the platform, redeemable anywhere.
3 separate errands done in one physical stop. Retailers reduce last-mile delivery costs. James never needed a bank card or a separate collection app.
Agnes – Elderly resident, needs her pension and a council service
Traditionally: two separate agencies, two visits, forms in formats she can't navigate online, cash-only options disappearing.
Agnes visits the local Phygital Community HUB. She authenticates via a palm vein scan – no PIN to remember, no phone required.
She accesses her pension account, withdraws cash from the integrated ATM, and checks her balance – all governed by the same session and audit trail.
From the same kiosk, she renews her bus pass, pays a council bill, and registers for a local service – three government agencies, one authenticated session.
One visit. No smartphone. No digital literacy required. Full dignity of service preserved. DPI achieved – sustainably funded by commercial tenants on the same infrastructure.
David – Chronic condition patient, managing a repeat prescription
Traditionally: GP visit for repeat prescription, pharmacy queue, manual insurance claim, paper trail fragmented across systems.
David's oneWallet notifies him his prescription is due. He approves the repeat via the app – his consented health record authorises the request automatically with the GP system.
His medication is ready at the LockerShop near his workplace. Biometric collection with temperature-controlled compartment – no pharmacist queue, no signature paper form.
The LAHE record of collection automatically triggers his insurance claim – machine-to-machine, with no form submission and a DBOM-verified data trail for the insurer.
Zero GP visits for routine repeats. Zero pharmacy queues. Instant insurance settlement. David's data never leaves the governed platform perimeter – full privacy preserved.
Fatima – Smallholder farmer, selling maize at the co-op
Traditionally: cash-only market, no credit history, exploitative middlemen, no access to formal banking or input finance.
Fatima brings her harvest to the co-op. The Agri POI appliance weighs and grades her produce automatically, generating a verified digital record of quantity and quality.
Payment is settled instantly to her oneWallet – governed by the co-op's Agreement DAGs, with transparent pricing locked in at the point of grading. No middleman margin.
Her verified transaction record builds a formal credit identity over time – enabling her to access input finance, crop insurance, and savings products from FSI tenants on the platform.
First formal banking relationship. Transparent pricing. Traceable produce supply chain for buyers. Agentic AI monitors her crop patterns and suggests optimal input purchasing – genuine financial inclusion.
Phygital Service Arbitrage
Phygital Service Arbitrage is the economic engine of the platform. It describes the value created when a digital service is delivered through a physical touchpoint in a way that is more cost-effective, more accessible, or more commercially valuable than either channel alone could achieve.
Consider: a digital service costs £0.002 per transaction to process but requires a smartphone and internet connectivity. A branch interaction costs £15. The POI appliance delivers the digital service in a physical context for £0.08 – capturing the value of both while excluding neither customer segment.
Multi-tenancy multiplies this. A single POI appliance used by a bank, a pharmacy, a government agency, and a retailer simultaneously transforms the unit economics of each deployment – making commercially viable the locations that no single tenant could justify alone.
Traditional Branch
£15 / interactionHigh cost, limited hours, limited geographic reach
Digital Only
£0.002 / interactionLowest cost, but excludes 1.4B unbanked and digitally excluded
Phygital POI (Multi-tenant)
£0.08 / interactionNear-digital cost, physical accessibility, commercially sustainable in any location
Ready to explore your Phygital opportunity?
Begin with a Discovery & Positioning Workshop to identify your optimal POI appliance mix and tenant cohort position.
Phygital Channels & Edge Ingress
Bridges physical edge interaction devices with the System of Engagement (SoE) through unified, high-assurance CEN XFS4IoT channels.
Seamless Continuity Across Mobile, Web, and Physical Spaces
The phygital network connects your phone and computer directly with physical touchpoints. You can start a transaction on your mobile device at home, and easily complete it at a local smart kiosk, locker, or drive-through without having to restart the process. This creates a smooth, continuous experience that keeps your session secure at every step. Note: the system guarantees execution of the programmed rules as written, but does not judge whether the rules themselves are good – that remains a human responsibility.
Pooled-Infrastructure Economics & Omnichannel State Synchronisation
The phygital layer operates as a multi-tenant, pooled-infrastructure model. By sharing physical terminals across multiple institutions, tenants achieve up to 80% CapEx savings compared to dedicated single-tenant networks. Secure session synchronisation (which we call inConcert) guarantees zero-bleed cross-tenant isolation while maintaining state continuity across mobile, web, and physical channels. This allows low-latency transaction routing and offline capability under a unified trust framework, ensuring all customer transactions are forensically recorded, fully attributable, and impossible to hide.
Compliance Frameworks
Native compliance logic alignment mapping to PSD3, eIDAS 2.0, and DORA resilience guidelines.
Commercial Pooled ROI
Shared physical infrastructure distribution model reducing CapEx overhead by up to 80%.
Architectural Integration (Symphony of Systems)
The phygital layer integrates active edge peripheral channels (biometrics, cash recyclers, document scanners) directly with the Symphony of Systems (SoS):
Peripheral hardware exposes interfaces as isolated localhost-bound WebSockets using the CEN XFS4IoT standard, preventing physical bus tapping and memory snooping.
Physical inputs drive transitions in Agreement DAGs (SoA), which are executed by the System of Orchestration (SoO) only when hardware attestation tokens resolve as valid.
Physical telemetry and sensory state hashes are logged on the bitemporal ledger in the System of Record (SoR) for validation by the System of Intelligence (SoI).
Ephemeral Session Wands & Physiological Liveness
TPM-Signed Ephemeral Session Wands
Every physical transaction triggers the creation of a temporary cryptographic assertion token (session wand). The wand is signed by the local TPM 2.0 and bound to the session's active hardware state. No persistent credentials are left behind on the terminal.
CEN XFS4IoT Device Partitioning
Hardware peripherals are isolated via secure local ports. Cross-tenant isolation is maintained dynamically, ensuring that competing tenant applications running on the same physical terminal cannot tap, capture, or intercept sensory inputs.
Remote Physiological Liveness (rPPG)
Using multi-spectral optical cameras, the system senses sub-visual micro-colour variations in skin tissue corresponding to cardiac pulse cycles. Dynamic wavelength shift analysis verifies human presence and blocks high-resolution 2D/3D presentation attacks.
Edge Enclave measured boot
Terminal OS operates with measured boot PCR registers. If any tampering with XFS4IoT drivers is detected, the enclave refuses to load, turning the device into a governed closed brick.
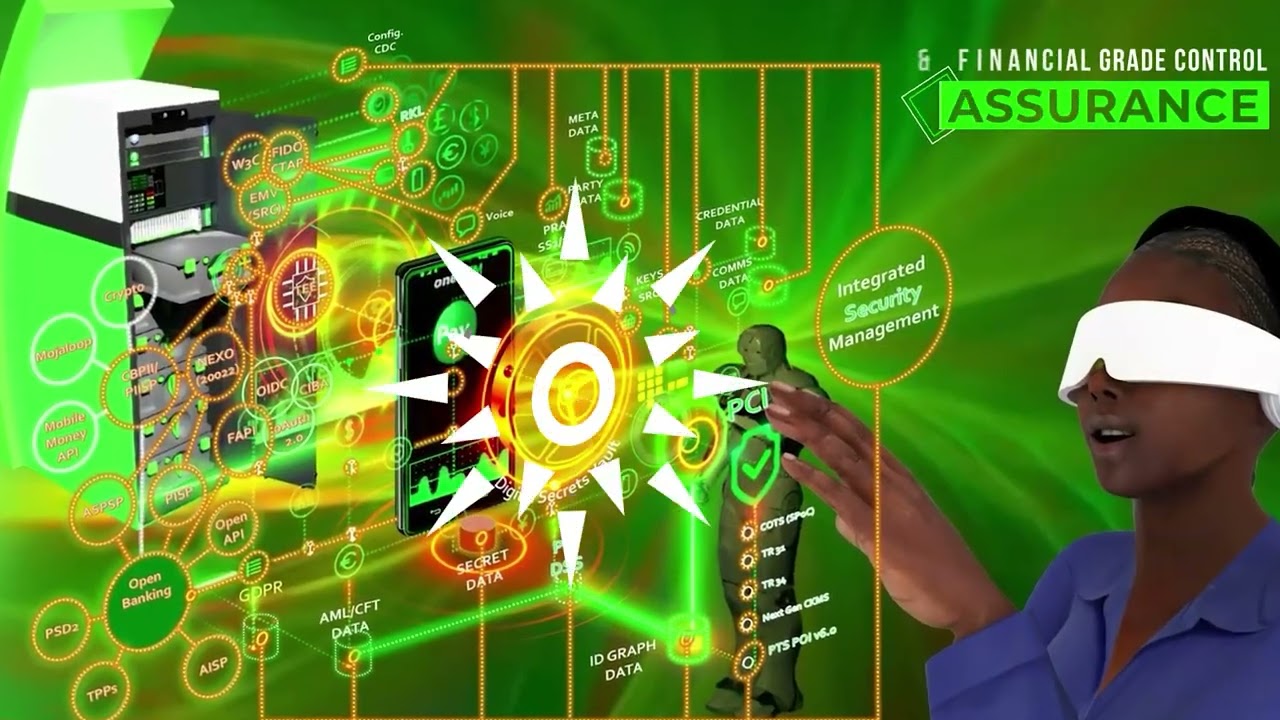
Examine how onePOI secures the boundary between digital banking code and physical hardware peripherals. Combining measured boot PCR enforcement, User and Entity Behaviour Analytics (UEBA), and cryptographically signed CEN XFS4IoT peripheral commands, the system immunises edge appliances against black-box jackpoting, skimming, and physical DMA bus taps.
Physiological Liveness & TPM Verification Proof
The platform formally guarantees edge terminal integrity and physiological liveness via cryptographic measured boot and optical wavelength shift verification.